Call our Alabama Divorce Attorneys about Marital Debt today at (205) 201-1789

The Harris Firm LLC handles debt division in contested and uncontested divorces across Alabama. Consultations are $100 by phone or in person.
In short: Alabama courts divide marital debts the same way they divide marital assets — equitably, not automatically fifty-fifty. Debts taken on during the marriage for the family’s benefit are generally marital obligations, regardless of whose name is on the account. Debts from before the marriage, and debts one spouse ran up on purely personal pursuits, can be assigned to that spouse alone.
How it works: The court — or the parties in a settlement — assigns each debt to a spouse alongside the asset division: the house payment follows the house, the car note follows the car, the cards get allocated. The agreement should also say how: refinance deadlines, account closures, and hold-harmless language with teeth.
The critical catch: a divorce decree binds the spouses, not the creditors. If both names are on the mortgage or the card, the lender can pursue either of you no matter what the decree says. Your protection is the decree’s enforcement power over your ex — and smart drafting that removes your name from the debt entirely wherever possible.
The biggest mistake: leaving joint accounts open and joint debts unrefinanced after the divorce. Every month your name stays on your ex’s obligations, their missed payment is your credit score, and their default is your lawsuit. Close it, refinance it, or secure it — before the decree is final, not after.
Related Pages for Dividing Assets & Debts
Property Division Overview
Equitable distribution in Alabama — the framework that governs assets and debts alike.
Property Division Overview →
Digital Assets
Crypto, online accounts, and the other side of the modern marital ledger.
Digital Assets →
The Marital Home
Keeping it, selling it, refinancing it — and the mortgage that comes with it.
The Marital Home →
Quit Claim Deeds
Moving the deed without moving the note — and why sequence matters.
Quit Claim Deeds →
Personal Property
Vehicles and accounts — the assets the car notes and card balances attach to.
Personal Property →
Debts Get Divided Like Assets — Equitably, Not Equally
Alabama is an equitable distribution state, and the same logic that divides what a couple owns divides what they owe. There is no automatic 50/50 split and no rule that the name on the account decides who pays. Courts look at when the debt arose, what it bought, who benefited, and each spouse’s ability to pay — then assign the obligations as part of the overall division, weighing them against the assets each spouse receives.
The starting classification runs parallel to property. Debt from before the marriage — a student loan, a car note, a credit card balance one spouse brought to the wedding — generally stays that spouse’s separate obligation. Debt taken on during the marriage for the common benefit — the mortgage, the family vehicles, the card that paid for groceries and school clothes — is generally marital, even if only one spouse signed. A wife who never touched the Home Depot card still shared the kitchen it remodeled; a husband who never saw the Visa statement still ate the meals it bought.
The exception cuts the other way, and it matters: debt one spouse ran up on purely personal pursuits — gambling, an affair, secret spending sprees, business ventures concealed from the other spouse — can be assigned entirely to the spender. Courts treat this the way they treat dissipation of assets: money burned on conduct outside the marriage does not become the innocent spouse’s problem just because it happened during the marriage. Proving it takes statements and dates, which is one more reason the debt inventory in these cases has to be as thorough as the asset inventory.
Your Divorce Decree Does Not Bind Your Creditors
This single distinction explains most post-divorce debt disasters. Learn it before you sign anything.
What the Decree Does
It creates enforceable obligations between the spouses. If the decree assigns the joint card to your ex and they stop paying, they are violating a court order — you can haul them back before the judge, seek contempt, and recover what their default cost you. Paired with a hold-harmless clause, the decree is your sword against a nonpaying ex.
What It Cannot Do
It cannot change your contract with the lender. If both names are on the mortgage, the card, or the car note, the creditor can pursue either of you — collections, lawsuits, credit damage — no matter what the decree says. The bank was not a party to your divorce and is not bound by it. Only refinancing, paying off, or closing the account actually removes your name from the risk.
Mortgages, Cars, Cards, and Taxes — How Each One Actually Gets Handled
The mortgage. When one spouse keeps the house, the standard structure is a refinance requirement with a deadline: the keeping spouse refinances the mortgage into their own name within a set period — commonly six months to a year — or the house gets sold. Without that language, the leaving spouse can stay on the note for decades, unable to qualify for their own mortgage because the old one still counts against them. And understand the two-document problem: a quit claim deed transfers ownership of the house, but it does nothing to the mortgage. Signing away the deed while staying on the note is the worst of both worlds — all of the liability, none of the asset.
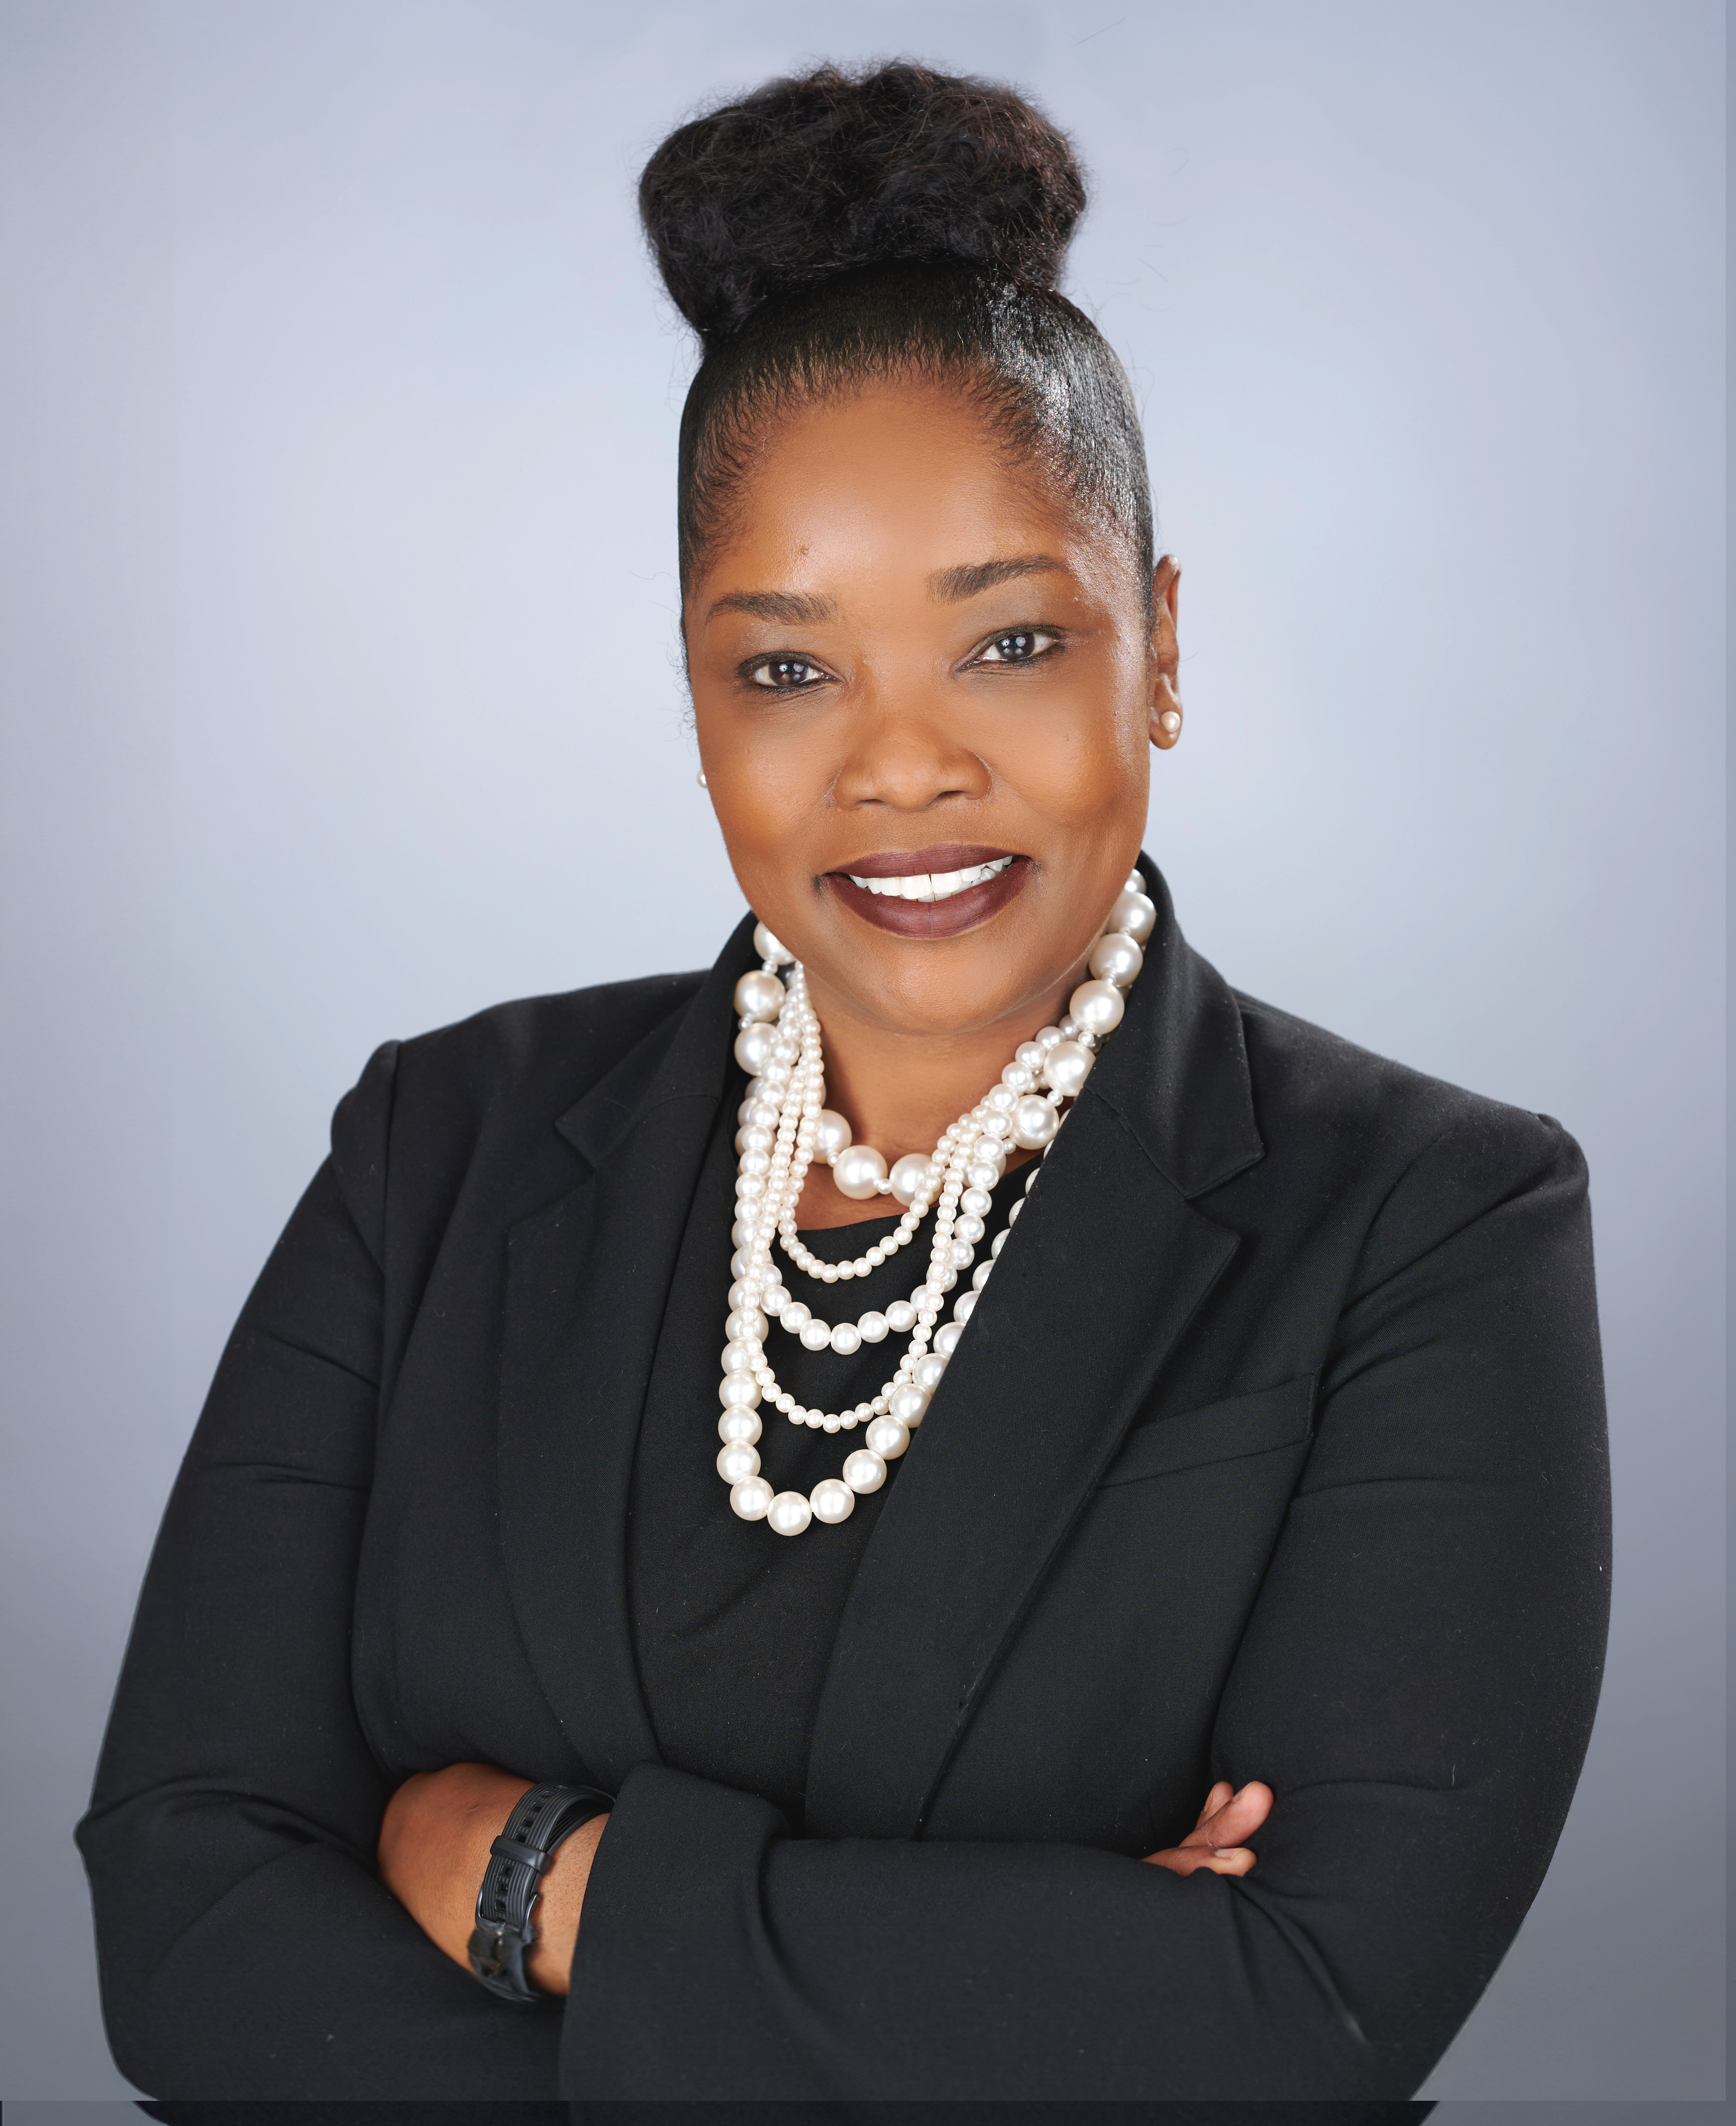 Vehicles and cards. Car notes follow the car: whoever keeps the vehicle takes the payment, refinancing into their own name where the lender allows it. Credit cards get allocated by balance as of a stated date — and joint cards get closed before the decree is final, full stop. Attorney LaTasha Huffman structures these settlements out of our Huntsville office, and her rule is that every debt line in the agreement answers three questions: who pays it, by when is the other spouse’s name off of it, and what happens if they do not. An agreement that only answers the first question is an invitation to litigation.
Tax debt. If you filed jointly, the IRS holds both spouses fully responsible for the entire liability on those returns — joint and several liability — and, like every other creditor, the IRS is not bound by your decree. The agreement should assign responsibility for known balances and for any later audit of the joint years, and a spouse blindsided by a partner’s underreporting may have innocent spouse relief available on the federal side. Business debts carry their own wrinkle: loans in the company’s name often ride with whoever keeps the business interest, but personal guarantees signed by both spouses survive the divorce like any other joint contract and need the same name-removal treatment.
Student Loans — and What Happens When an Ex Stops Paying
Student loans mostly follow the borrower. Loans from before the marriage are separate debt, plainly. Loans taken during the marriage usually stay with the spouse whose education they funded — the degree, the license, and the earning power leave the marriage with that spouse, so the debt generally does too. Courts can weigh it differently where the family genuinely lived on the loan money or where the supporting spouse sacrificed heavily for the degree, but the working presumption in most cases is that your ex’s student loans are not becoming your problem.
Enforcement is the other half of this page, because a debt assignment is only as good as your remedy when it fails. If your decree ordered your ex to pay a joint debt and the collection calls are coming to you, the tool is a contempt action — a rule nisi petition asking the court to enforce its own order. Courts can order payment, enter judgments for what the default cost you, award attorney fees, and jail a willfully noncompliant ex in the worst cases. What you should not do is nothing: your credit absorbs the damage month by month while you wait, and the paper trail you keep — statements, collection letters, proof you had to cover payments — is exactly what wins the contempt hearing.
A note on bankruptcy: if an ex-spouse files bankruptcy after the divorce, obligations owed to a former spouse under a divorce decree receive special protection in bankruptcy law — but the interaction is technical and the creditor can still be at your door in the meantime. If bankruptcy enters the picture on either side, get advice immediately rather than assuming the decree settles it.
How We Handle Debt Division
The debts get the same discipline as the assets — inventoried, classified, assigned, and secured.
Pull Both Credit Reports
The full debt inventory starts with both spouses’ credit reports — the fastest way to surface accounts one spouse forgot, or never knew about.
Classify Marital vs. Separate
Pre-marital debt, common-benefit debt, and personal-pursuit debt — each with dates, balances, and the statements to back the classification.
Assign Debts Alongside Assets
The note follows the car, the mortgage follows the house, and the net division — assets minus assigned debts — is what actually has to come out equitable.
Set Name-Removal Deadlines
Refinance deadlines on the mortgage and vehicles, closure of every joint account, and a sale trigger if a refinance fails — written into the agreement, not left to goodwill.
Draft Hold-Harmless Language with Teeth
Each spouse indemnifies the other on their assigned debts — so a default becomes a court-enforceable claim for everything it costs you, including attorney fees.
Enforce When an Ex Defaults
Contempt petitions for assigned debts that go unpaid — payment orders, judgments for the damage, and fee awards against the defaulting spouse.
Frequently Asked Questions About Marital Debt Division
1.How is debt divided in an Alabama divorce?
Equitably, alongside the assets — not automatically fifty-fifty and not by whose name is on the account. Courts look at when the debt arose, what it paid for, who benefited, and each spouse’s ability to pay. Debts incurred during the marriage for the family’s benefit are generally marital; pre-marital debts and purely personal spending generally stay with the spouse who incurred them.
2.Am I responsible for credit card debt that is only in my spouse’s name?
The creditor generally cannot pursue you for an account you never signed — but the divorce court can still assign that debt within the division if it was marital spending, adjusting the property split accordingly. The reverse is also true: a card in your name that funded family expenses can be allocated partly to your spouse. Contract liability and divorce allocation are two separate questions.
3.What happens to the mortgage when my ex keeps the house?
Your agreement should require them to refinance the mortgage into their own name by a firm deadline, with the house sold if they cannot. Until a refinance happens, you remain fully liable to the lender no matter what the decree says, and the payment counts against you when you seek your own credit. Never sign over the deed while your name is still on the note without that protection in writing.
4.My ex was ordered to pay a joint debt and stopped paying. What can I do?
File a contempt action asking the court to enforce its own order. Courts can order payment, enter a judgment for what the default cost you — covered payments, fees, credit damage — and sanction a willfully noncompliant ex. Meanwhile, protect your credit: creditors on joint accounts can still pursue you, so sometimes the practical move is covering the payment and recovering it through the contempt case. Keep every statement and collection letter.
5.Who pays student loans in an Alabama divorce?
Usually the spouse who borrowed them. Pre-marital student loans are separate debt, and loans taken during the marriage generally follow the spouse whose education they funded, since the degree and its earning power leave with them. Courts can weigh the equities differently where loan money genuinely supported the household, but the working presumption is that each spouse keeps their own education debt.
6.What happens with IRS debt from our joint tax returns?
Joint returns carry joint and several liability — the IRS can collect the full amount from either spouse, and your divorce decree does not change that. The agreement should assign responsibility for known balances and any later audits of the joint years, enforceable between the spouses. A spouse blindsided by the other’s underreporting may qualify for innocent spouse relief with the IRS, which is a separate federal process worth pursuing in the right case.
Debt Division Cases Across Alabama
Protect Your Credit Before the Decree Is Final
The time to fix a debt division is while it is being drafted — refinance deadlines, account closures, and hold-harmless language cost nothing to include and everything to litigate later. A $100 consultation gets your full debt picture mapped and a division structured to protect you after the ink dries.
What We Handle
✓ Debt inventories, classification, and dissipation claims
✓ Mortgage refinance terms and deed-and-note coordination
✓ Credit card, vehicle, tax, and business debt allocation
✓ Hold-harmless and indemnification drafting
✓ Contempt enforcement when an ex stops paying
Call the Office Nearest You
Birmingham: (205) 201-1789
Chelsea: (205) 677-5490
Montgomery: (334) 782-9938
Huntsville: (256) 665-9473
Dividing the whole estate? Start with the property division overview, and see digital assets for the modern side of the ledger.
Harris Firm LLC Proud Member of